

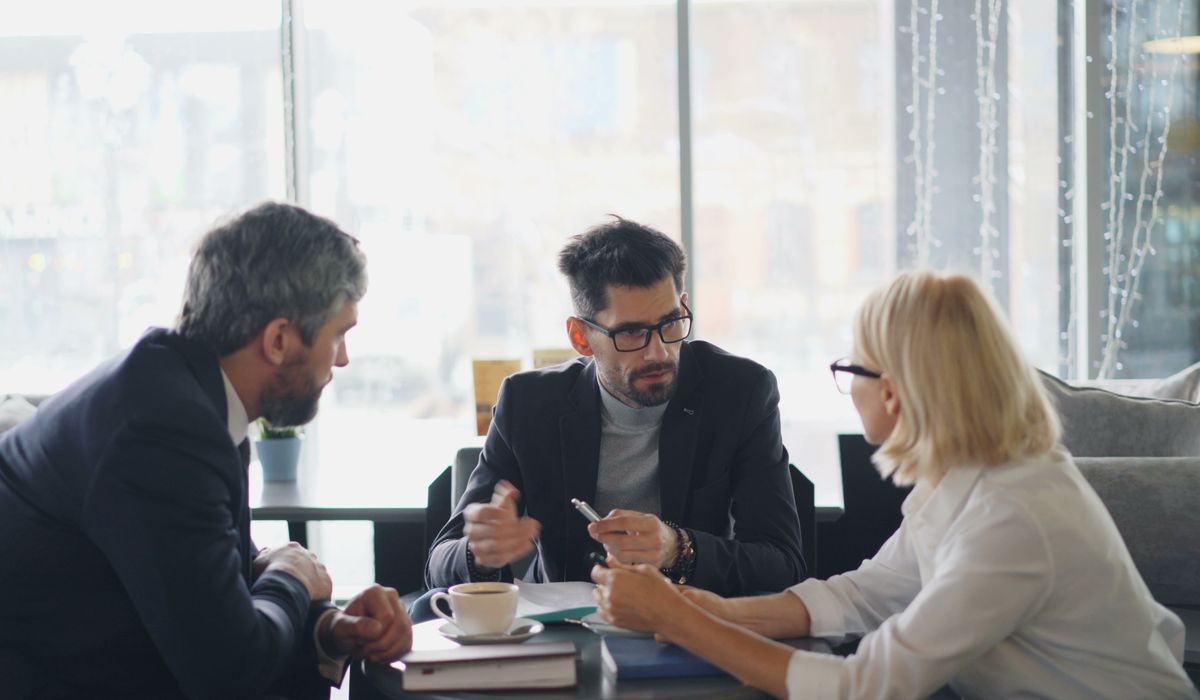
Investing in a franchise is a significant commitment, both financially and personally. Before you sign on the dotted line, you need to understand exactly what you are buying into. In the UK, unlike some other countries, there is no single legally mandated franchise disclosure document. However, reputable franchisors – particularly those who are members of the British Franchise Association – will provide a comprehensive disclosure document or franchise prospectus. This document is your most important tool for due diligence. It sets out the fees, territory rights, obligations, and much more. Reading it carefully, and asking the right questions, can save you from costly mistakes.
What a Franchise Disclosure Document Includes in the UK
While the format varies, a good disclosure document should give you a complete picture of the franchise opportunity. It typically covers the franchisor’s background, the history of the network, the initial and ongoing costs, the territory you will be granted, your obligations as a franchisee, and the support you can expect. It should also explain what happens if you want to sell, renew, or exit the agreement. In the UK, the British Franchise Association’s code of ethics requires members to provide full and accurate written information before a contract is signed. If a franchisor is reluctant to share this information, treat that as a serious warning sign.
The Fees You Will Pay – and When
Fees are often the first thing people look for, and for good reason. But it is not just the headline figure that matters. You need to understand every payment, when it is due, and what it covers. Look out for these common charges:
- Initial franchise fee: a one-off payment for the right to join the network. Check whether it is refundable and what it includes, such as training or equipment.
- Ongoing management services fee (royalty): usually a percentage of turnover, paid monthly or quarterly. Confirm whether it is based on gross or net sales.
- Marketing or advertising levy: a separate contribution, often a percentage of turnover, used to promote the brand. Ask how it is spent and whether you have any say.
- Training fees: some franchisors include initial training, others charge extra for additional staff or refresher courses.
- Renewal and transfer fees: if you want to extend your agreement or sell your franchise, there may be a fee. Get the amounts in writing.
- Insurance and equipment: you may be required to buy specific insurance or equipment from approved suppliers, which can be more expensive than the open market.
Add up all these costs, not just the initial fee. A franchise that looks cheap upfront may have high ongoing charges that eat into your profits.
Territory Rights: What You Get and What You Don’t
Your territory is your patch – the area where you can operate and, ideally, where no other franchisee can compete. The disclosure document should define this precisely. Is it exclusive, meaning the franchisor cannot sell another franchise in your area? Or is it non-exclusive, meaning you could face competition from fellow franchisees or even the franchisor’s own online sales? Check the boundaries: postcodes, radius, or a map. Also ask about online sales, national accounts, and mobile or home-based operations. If you are buying a territory, you need to know what protection you have. Some agreements include a right of first refusal if the franchisor wants to sell an adjacent area. Others may allow the franchisor to change your territory with little notice. Read the small print carefully.
Your Obligations as a Franchisee
The disclosure document also spells out what you must do. These obligations are just as important as your rights, because failing to meet them can lead to termination. Typical obligations include:
- Operating standards: you must follow the franchisor’s systems, branding, and quality controls.
- Opening hours: you may be required to open minimum hours, including weekends or evenings.
- Approved suppliers: you might have to buy stock or materials from nominated suppliers, which can limit your ability to shop around.
- Reporting and audits: you will need to submit regular financial reports and allow the franchisor to inspect your records.
- Personal involvement: some agreements require you to work in the business full-time, rather than being an absentee owner.
- Non-compete clauses: you may be restricted from running a similar business in the area for a period after the franchise ends.
Make sure you can live with these obligations. If something feels unreasonable, raise it before signing. A good franchisor will explain the reasoning and may be flexible.
Red Flags and Smart Questions to Ask
Not every disclosure document is created equal. Watch out for vague language, missing financial details, or pressure to sign quickly. If the document does not include a clear breakdown of fees, territory, and obligations, ask for it in writing. Be wary if the franchisor cannot provide names of existing franchisees to speak to, or if those franchisees are reluctant to share their experiences. Other red flags include no mention of what happens if you want to sell, no details about renewal terms, and a lack of British Franchise Association membership. Before you commit, ask:
- What support do I get in the first six months, and what does it cost?
- How is my territory protected from other franchisees and online sales?
- What are the exact renewal conditions, and can they change?
- What happens if I want to sell my franchise – who approves the buyer and what fees apply?
- Can I speak to two or three franchisees who have been in the network for at least two years?
Getting Professional Advice Before You Commit
A franchise disclosure document is a legal and financial roadmap. It is not light reading, and it is easy to miss something important. That is why you should always have it reviewed by a solicitor who specialises in franchising, and an accountant who can check the financial projections. Their fees are a small price to pay for peace of mind. Also, take your time. A reputable franchisor will respect your need to do proper due diligence. If they rush you, walk away. Investing in a franchise can be a rewarding way to run your own business with support, but only if you understand exactly what you are signing up for. Read the document, ask questions, and get expert help. Your future self will thank you.


John Doe
14 January, 2022Having no content in post should have adverse..
Chauffina Carr
10 April, 2022We use these tests all time! Killer stuff!
Jim Séchen
16 July, 2022Thanks for all the comments, everyone!